Tampa, FL
HELOC vs Cash-Out Refinance in Tampa, FL: 2026 Guide
Not sure whether a HELOC or cash-out refinance makes sense in Tampa? Compare 2026 rates, structures, and tradeoffs to find the right fit for your equity.
8 min
Expert guides, loan-option breakdowns, and local market insights from Bay to Bay Lending.
Not sure whether a HELOC or cash-out refinance makes sense in Tampa? Compare 2026 rates, structures, and tradeoffs to find the right fit for your equity.
From buying discount points to refinancing, here are four practical ways to lower your mortgage rate in Tampa right now — with real numbers to guide your decision.
The 43% DTI limit on FHA loans is a myth. Tampa buyers may qualify with back-end ratios up to 56.99% — here's what the rules actually say.
In South Tampa's high-price market, an independent mortgage broker often beats a big bank on rate and flexibility — here's how the matchup plays out.
VA loans offer zero down and no mortgage insurance for eligible Tampa buyers, but conventional loans have advantages too. Here's how to choose in 2026.
VA loans give Tampa veterans a powerful path to homeownership — no down payment, no PMI, and lower closing costs. Here's what to know in 2026.
FHA loans in Tampa allow 3.5% down up to a $524,225 limit for Hillsborough County. Learn who qualifies and when FHA makes sense in this market.
Should Tampa buyers call a mortgage broker or go straight to a lender? This 2026 guide breaks down the real differences so you can choose wisely.
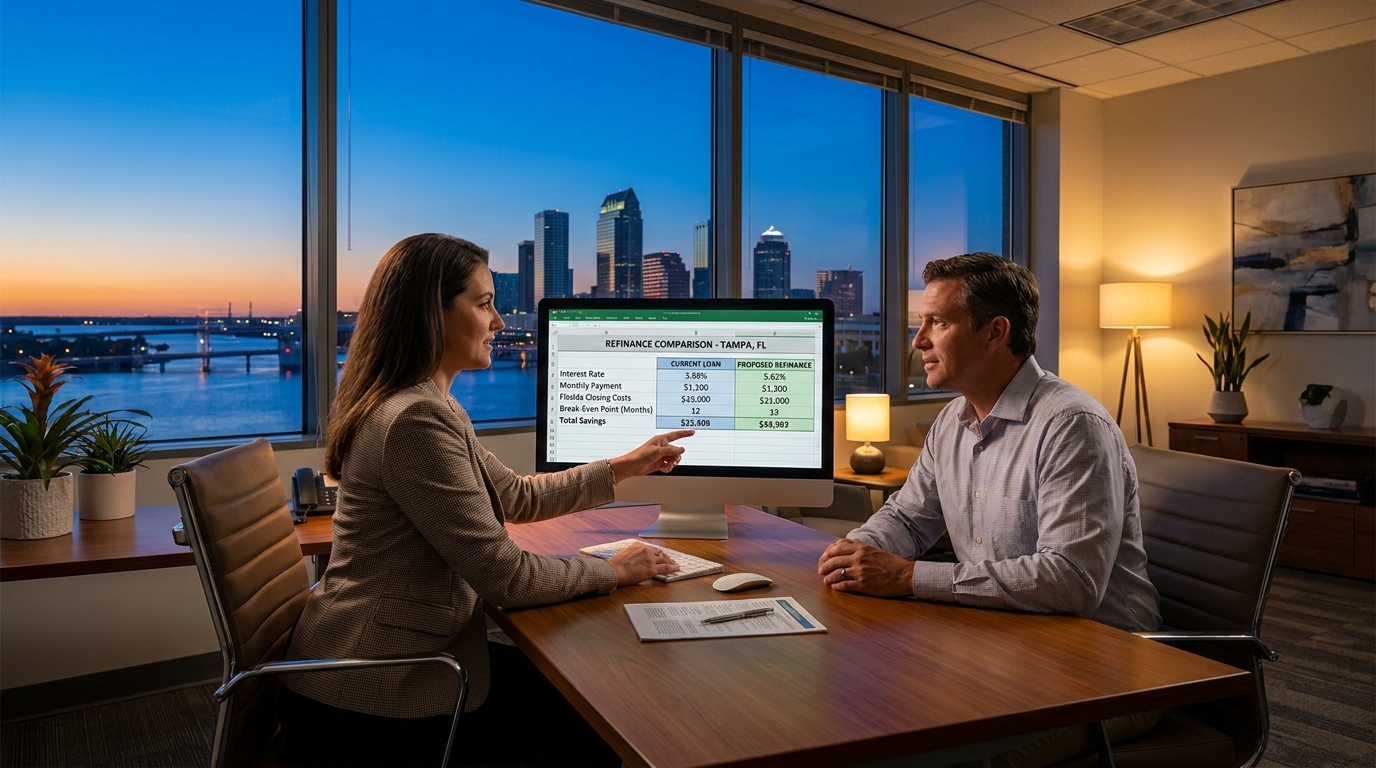
Not every Tampa homeowner should refinance in 2026. Learn which rate, loan type, and equity profiles make it a clear win — and when waiting saves you more.
From pre-approval to closing, here's exactly how the mortgage process works for first-time buyers in Tampa — including the local surprises that can derail your budget.
Tampa HELOCs look affordable at first glance, but variable rates, payment shock, and Florida-specific taxes add up fast. Here's what to expect.
From conventional loans to DSCR financing, here's how Tampa rental property investors actually structure their purchases and scale their portfolios.
Tampa mortgage broker fees run 1–2% of your loan and appear differently depending on who pays. Here's how to read every line on your Loan Estimate.
Self-employed Tampa buyers qualify faster through a mortgage broker than a retail bank — brokers unlock bank-statement loans and non-QM programs most banks don't offer.
A Tampa construction loan funds your build in stages with interest-only payments. Here's how draws, costs, and lender requirements actually work.
A mortgage broker shops your loan across dozens of lenders so you get lower rates and fees than any single bank can offer.
Wondering what credit score you need to buy a home in Tampa? From FHA minimums to conventional thresholds, here's what actually gets you approved in 2026.
Qualifying for a Tampa home loan in 2026 comes down to income, credit, DTI, and your loan program. Here's how each piece fits together in Tampa's market.
Buying a rental in Tampa means clearing three big hurdles: down payment, six-month reserves, and debt-to-income ratios. Here's what lenders actually require.
In Tampa, mortgage pre-approval typically takes 1–3 business days and moves through five key stages. Here's what to expect and how to fast-track your letter.
Tampa mortgage brokers charge 0.5%–2% borrower-paid or 1%–2.75% lender-paid — here's how to know which model actually costs you less.
A Florida HELOC lets you borrow against home equity as a revolving credit line, but homestead laws add unique signing rules and lender rights Tampa homeowners must know.
Brandon home buyers in 2026 can tap FHA loans with 3.5% down or $0-down VA financing — here's how each loan works and which one fits your situation.
Broker or direct lender? In St. Petersburg's assistance-heavy market, the right choice depends on which programs you plan to use and how complex your loan is.
From W-2s to flood zone disclosures, here's the complete mortgage document checklist for Tampa buyers in 2026.
The right questions can save you thousands and prevent a deal from falling apart. Here's what to ask any Tampa mortgage broker before you commit.
Refinancing in Tampa isn't one-size-fits-all. Learn the key differences between rate-and-term and cash-out refinances to find the right fit for your goals.
Not all first-time buyer loans work the same in Tampa. Compare FHA, USDA, and Florida Housing Bond programs to find your best fit.
Refinancing can save St. Petersburg homeowners thousands — but only if the timing is right. Here's how to calculate your break-even and decide with confidence.
Refinancing in Tampa follows a predictable path. Here's a clear, step-by-step walkthrough of what the process actually looks like for Florida homeowners in 2026.
Your bank can only offer its own rates — but a Florida mortgage broker shops dozens of lenders to find you a better deal.
Wondering if a mortgage broker can help with your VA loan in Brandon, FL? Here's how broker access to wholesale lenders gives military buyers a real advantage.
Choosing between FHA and conventional loans in Tampa comes down to your credit score and savings. Here's an honest breakdown to help you decide.
Not all Tampa mortgage broker rankings are created equal. Here's what the criteria actually mean and how to compare brokers like a careful buyer.
Not all mortgage lenders work the same way. Here's how brokers and bankers differ in Tampa — and which one could save you thousands.

Before applying for an FHA loan in Clearwater, organizing your documents is everything. Here's exactly what to gather so your file moves fast.
With Tampa's median home price near $443K, choosing the wrong mortgage broker can cost you thousands. Here's how to vet one you can actually trust.

Navigating first-time home buyer loans in St. Petersburg? Break down your real local options — FHA, VA, and more — in a market that plays by its own rules.
Big banks often deny self-employed borrowers based on tax returns alone. A local Brandon mortgage broker can match you with loans built for how you actually earn.

Financing a 1925 Seminole Heights bungalow isn't like buying a new build. Here's how to choose the right mortgage lender for Tampa's unique older neighborhoods.

Buying a home in Citrus Park? Here's how mortgage brokers and direct bank lenders actually compare — and how to choose the right path for your purchase.

A step-by-step VA loan eligibility checklist built for St. Petersburg buyers — covering federal service requirements, Florida-specific steps, and Pinellas County closing details.
Investment property mortgages come with stricter rules than primary home loans. Here's what Sarasota buyers need to know before financing a rental.
Rates have shifted and Clearwater home values have moved—here's how to decide if refinancing actually pencils out for you in mid-2026.

Buying in Palma Ceia means finding a lender who understands South Tampa's competitive market. Here's how to compare your mortgage options effectively.
Not all refinance lenders are equal in Westchase. Learn which lender type — broker, bank, or credit union — gets Tampa homeowners the best rate for their situation.

Before you make an offer in Beach Park, you need a pre-approval letter. Here's exactly what Tampa lenders look for and how the process unfolds.
FHA or conventional? Ballast Point buyers face this fork every time. Here's how to choose based on your credit score, down payment, and long-term costs.
Navigate Sarasota's unique investment property financing landscape, from hurricane insurance to flood zones and post-Surfside condo regulations.
Most mortgage delays are avoidable. Learn how to speed up your Tampa mortgage approval and close in 21 days instead of 45.
Learn FHA loan requirements for Tampa Bay homebuyers, including credit score minimums and down payment options for the local market.
Navigate Brandon's unique housing market with confidence using our mortgage broker selection checklist and local market insights.
Learn when and how to change mortgage lenders during your loan process in Clearwater, including timing considerations and what it costs to start over.
Complete guide to first time home buyer programs in St Petersburg, including city assistance up to $75k and qualification requirements.
Sarasota's real estate market follows a predictable seasonal cycle driven by snowbirds, affecting prices and competition throughout the year.
Bridge loans help Brandon buyers purchase their next home before selling their current one by tapping existing home equity for temporary financing.
ARMs offer lower initial payments but variable rates, while fixed-rate mortgages provide payment stability throughout the loan term.
Getting denied for a mortgage isn't the end of your homebuying journey. Learn the most common rejection reasons and how to bounce back stronger.
Construction-to-permanent loans offer single-close financing that funds your build and converts to a mortgage, simplifying new home construction in Tampa.
Bank statement loans help self-employed borrowers qualify for mortgages using actual cash flow instead of tax return income after deductions.
Master the timing of mortgage rate locks with strategies based on your timeline and risk tolerance, not market predictions.
Tampa's luxury home market requires jumbo loans with stricter qualification requirements than standard mortgages.
Investment property financing in Brandon requires higher down payments, stricter qualification criteria, and different rates than primary residence loans.
Essential document checklist for mortgage pre-approval in Tampa's competitive market.
Choosing between mortgage brokers and banks in Clearwater? Discover which option saves more money based on your credit, property type, and timeline.
Learn about 3% down mortgage options in Sarasota, including conventional, FHA, VA, and USDA loans that help buyers avoid the traditional 20% down payment.
Master mortgage affordability calculations using debt-to-income ratios the way Tampa lenders do, including front-end and back-end ratio requirements.
Current Tampa mortgage rates range from 5.75% on 15-year loans to 6.78% on cash-out refis, with 30-year fixed at 6.50%.
Conventional loans in Brandon require as little as 3% down, but your credit score, property type, and local costs all affect what you'll actually need to bring to closing.
FHA loans help St Petersburg buyers with less cash and lower credit scores, but conventional loans can save thousands long-term. Find out which fits your situation.
VA loans offer military families unbeatable advantages including zero down payment and no PMI. Learn how to maximize this lifetime benefit in Tampa's market.

Get your Brandon home loan approved with the right credit score. Current 2026 requirements by loan type, plus insider tips from 15+ years in Manitoba mortgages.

FHA loans vs conventional loans for Tampa first-time buyers. Get the insider guide to loan options that actually work in today's market.

Get straight answers to your Tampa mortgage questions. VA loans, conventional options, and insider tips from a 15-year local broker.

Get Tampa's best refinance rates. Compare 15+ lenders, FHA vs conventional terms, and avoid costly mistakes most borrowers make.

Brandon mortgage broker reveals why most homebuyers choose the wrong loan type. Real differences between FHA and conventional loans that actually matter.

Get your St Petersburg mortgage approved faster. Credit score, income docs, and local lender secrets from a 15-year broker.

VA loans in St Petersburg offer zero down payment and no PMI. Learn eligibility requirements, benefits, and how to maximize your military homebuying advantage.