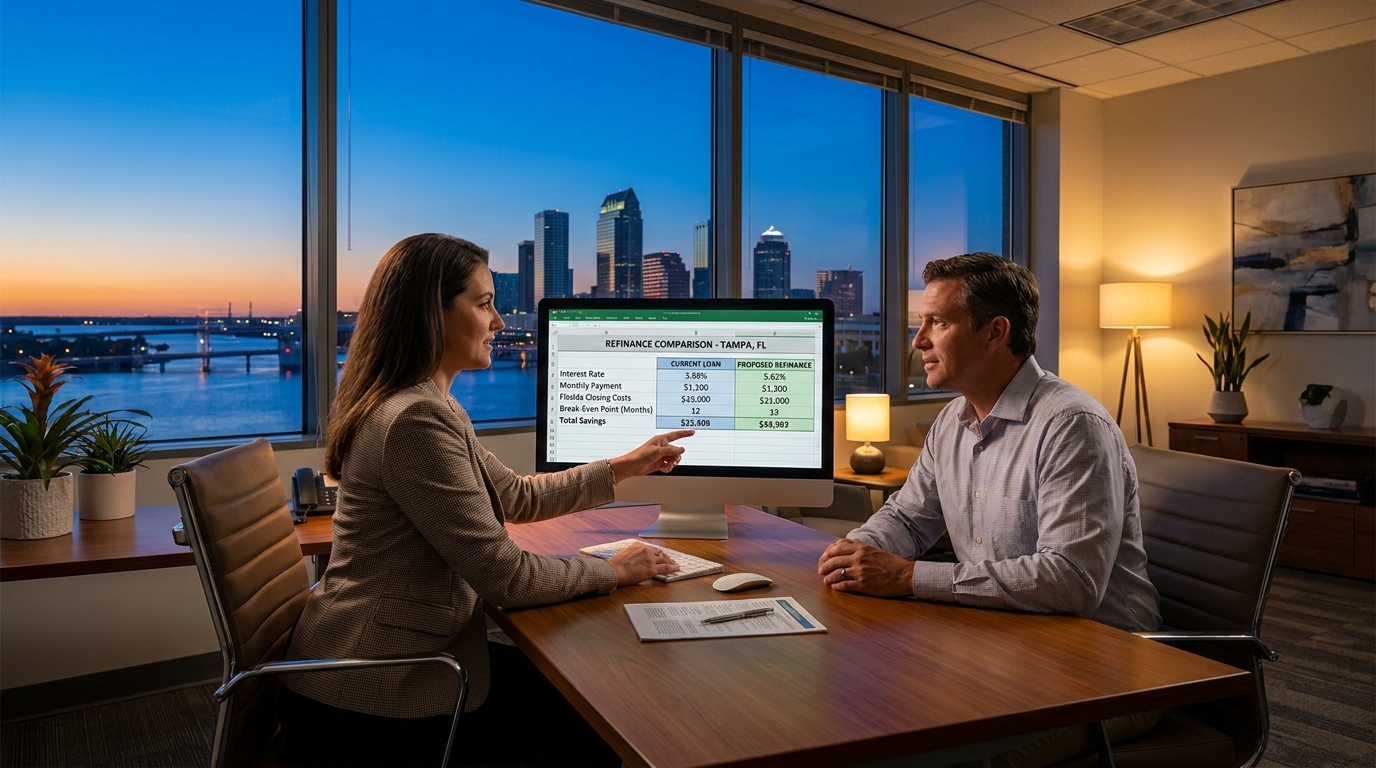
If you bought a Tampa home at a 6.5% to 7.5% rate in 2026 or 2026, hold FHA financing you'd like to shed, or have built serious equity in South Tampa or Seminole Heights, a refinance in 2026 may already pencil out. If you bought after mid-2026 at a rate near today's, plan to move within three years, or would only shave a quarter point off your note, waiting is almost always the smarter call.
That is the honest answer. The rest of this piece shows you how to run the math on your own file — including the Florida-specific costs most online calculators quietly ignore.
Which Tampa homeowners should refinance right now in 2026?
Refinance now if you meet one of three profiles: you locked a rate of 6.75% or higher in 2026-2026 and current pricing beats it by at least 0.75%, you carry FHA mortgage insurance and now have 20%+ equity to move into a conventional loan, or you need cash-out for a specific, higher-return use and the blended cost still beats alternatives.
The first group is the clearest win. Tampa saw a wave of purchases at peak rates between late 2026 and mid-2026, when 30-year fixed pricing sat between 6.5% and 7.5%. A drop of three-quarters of a point on a $425,000 balance saves roughly $200 a month — enough to clear typical Florida closing costs inside two to three years.
The second group is often overlooked. FHA mortgage insurance is now permanent on most loans originated after 2026, meaning it stays for the life of the loan regardless of equity. At Bay to Bay Lending we see this constantly with buyers who used FHA to get into neighborhoods like Riverside Heights or Old Seminole Heights when values were lower — they now hold 25% or 30% equity and are paying $180-$250 a month for insurance they no longer need. A conventional refinance drops that entirely.
Which Tampa homeowners should wait to refinance?
Wait if your current rate is within 0.5% of today's market, if you plan to sell or relocate within three years, if your credit score has slipped below 700 since your original loan, or if you'd be refinancing purely to lower a payment without accounting for Florida's documentary stamp tax and intangible tax on the new note. The savings math often collapses once those state costs are included.
Florida charges a documentary stamp tax of $0.35 per $100 of the new mortgage amount, plus a nonrecurring intangible tax of $0.002 per $1 of the loan. On a $400,000 refinance, that's $1,400 in doc stamps and $800 in intangible tax — $2,200 in state charges alone, before title, appraisal, or lender fees. Total Tampa closing costs on a rate-and-term refi typically land between $4,500 and $8,500.
How do I calculate my real break-even point on a Tampa refinance?
Divide your total closing costs by your monthly payment savings. If closing costs run $6,000 and you save $220 a month, break-even is 27 months. If you'll stay in the home longer than that break-even period, the refinance pays off. If you might move before then — common for households near MacDill AFB or corporate relocations through Westshore — the math usually says wait.
Two adjustments Tampa borrowers miss:
- Add the Florida state taxes to your closing cost figure. National calculators default to states without documentary stamp taxes and understate your true cost by roughly $2,000-$3,000 on a typical loan.
- Subtract escrow refunds carefully. Your old escrow account gets refunded within 30 days of payoff, but you'll fund a new escrow at closing. It's a wash in cash terms — don't count it as savings.
How does Florida's doc stamp tax change refinance math for investors?
Investors with non-homesteaded Tampa rentals face the same $0.35 per $100 documentary stamp tax and $0.002 per $1 intangible tax on the new mortgage, but they also lose homestead protection on assessed value caps. Rates on investment property refinances typically run 0.5% to 0.875% higher than owner-occupied pricing, which widens the break-even window considerably — often to 40+ months.
For a landlord holding a duplex in Seminole Heights or a single-family rental in Sulphur Springs, the calculus usually favors either waiting for a larger rate drop or considering a cash-out only when the freed capital funds another acquisition at a return that clearly exceeds the new blended borrowing cost.
Rate-and-term vs. cash-out refinance in Tampa: which makes sense?
Choose a rate-and-term refinance when your only goal is a lower rate or shorter loan term — closing costs are lower and pricing is more favorable. Choose a cash-out refinance only when you need $40,000 or more, have a defined use (renovation, debt consolidation at meaningfully lower blended cost, investment), and can't achieve the goal with a HELOC or second mortgage at lower total friction.
| Scenario | Best Fit | Typical Tampa Cost Range |
|---|---|---|
| Drop rate 0.75%+ from 2026-2026 purchase | Rate-and-term refinance | $4,500 - $7,000 |
| Remove FHA mortgage insurance | Rate-and-term to conventional | $5,000 - $7,500 |
| Pull $50K+ for major renovation | Cash-out refinance | $6,000 - $9,000 |
| Pull $30K-$75K for shorter-term need | HELOC (not refinance) | $0 - $1,500 |
| Shorten 30-year to 15-year term | Rate-and-term refinance | $4,500 - $7,000 |
| Investment property, rate drop under 1% | Wait | N/A |
If your need is under $75,000 or short-term, our companion piece on what a HELOC actually costs in Tampa walks through the second-lien option in detail — often a better fit than replacing your entire first mortgage.
What credit score and equity do Tampa lenders want for a refinance in 2026?
Most conventional refinances in Tampa require a minimum 620 credit score, though pricing tiers meaningfully improve at 680, 720, and 760. Lenders generally want at least 20% equity for the best conventional pricing and to avoid PMI, though FHA and VA streamline refinances allow higher loan-to-value ratios. Investment property refinances typically cap out at 75% LTV.
Tampa appraisals have stabilized after the 2026-2026 surge. Median single-family values across Hillsborough County still sit well above 2026 levels, so most homeowners who bought before 2026 hold substantial equity — often more than they realize. A quick appraisal estimate before you apply helps you know which loan programs you actually qualify for.
Frequently asked questions about refinancing in Tampa
How much does it cost to refinance a home in Tampa, FL?
Total closing costs on a Tampa refinance typically run $4,500 to $8,500 on a loan between $300,000 and $500,000. That includes Florida's documentary stamp tax ($0.35 per $100 of loan amount), intangible tax ($0.002 per $1), title insurance, appraisal ($550-$700), lender fees, and recording charges. Investment properties and jumbo loans push higher.
How long does a Tampa refinance take from application to closing?
Most Tampa refinances close in 30 to 45 days from a complete application. Appraisal scheduling is usually the longest single step, running 7 to 14 days in the current market. Title work on Florida properties moves relatively quickly because the state has a well-established title insurance and closing infrastructure. Streamline refinances on existing FHA or VA loans can close in as few as 21 days.
Can I refinance my Tampa home if I have FHA mortgage insurance?
Yes, and it's often the single strongest reason to refinance. FHA mortgage insurance premiums are permanent on most loans originated after 2026, meaning they never fall off even after you reach 20% equity. Refinancing into a conventional loan removes that MIP entirely, which frequently saves $150-$300 per month on typical Tampa loan sizes — sometimes more than the rate change itself.
Does Florida's documentary stamp tax apply to every refinance?
Yes. Florida charges documentary stamp tax on the new promissory note at $0.35 per $100 of the loan amount, plus a nonrecurring intangible tax of $0.002 per $1, on essentially every refinance that creates a new mortgage. There is no exemption for refinances of an existing loan on the same property. On a $400,000 refinance, that combined state cost is $2,200.
Should I refinance to a 15-year mortgage in Tampa?
Refinance to a 15-year loan if you can absorb the higher monthly payment comfortably, plan to stay in the home at least seven years, and value long-term interest savings over payment flexibility. 15-year rates typically run 0.5% to 0.75% below 30-year pricing, and the total interest saved over the life of the loan on a Tampa-sized mortgage is often $150,000 or more.
Is a cash-out refinance or HELOC better for a Tampa homeowner?
A HELOC is usually better for smaller amounts (under $75,000), shorter-term needs, or when you want to preserve a low first-mortgage rate. A cash-out refinance is better when you need larger sums, want fixed-rate certainty on the borrowed amount, or when current rates are actually lower than your existing first mortgage — a rare situation for anyone who bought before 2026.
The bottom line for Tampa refinancers
The refinance question in Tampa is not "are rates good?" — it's "do the numbers work on my specific loan, in my specific timeframe, with Florida's specific costs included?" For 2026-2026 buyers, FHA holders sitting on equity, and homeowners planning to stay put for at least three years, the answer in 2026 is often yes. For everyone else, waiting costs nothing.
Bay to Bay Lending works with Tampa homeowners across Hillsborough and Pinellas counties on exactly this decision — running the real break-even math on your file, comparing rate-and-term against cash-out and HELOC options, and telling you honestly when the answer is "not yet." One recent client described their team as truly having "our best interests in mind" through a comparable decision. Bay to Bay Lending holds a 4.6-star rating across 36 Google reviews. Homeowners in Tampa who want a straight read on their own refinance math can reach us at baytobaylending.com.