Tampa, FL
Conventional Loan for Self-Employed Borrowers in Tampa
Self-employed Tampa buyers can qualify for a conventional loan — but income is calculated from net, not gross. Here's what lenders need and how to prepare.
7 min
Mortgage and home-lending resources for Tampa, FL.
52 articles
Self-employed Tampa buyers can qualify for a conventional loan — but income is calculated from net, not gross. Here's what lenders need and how to prepare.
Tampa's 2026 conventional loan limit is $832,750 for a single-unit home. Here's what that means for buyers in Hillsborough County.
Tampa first-time buyers can put as little as 3.5% down with an FHA loan — but gift funds, assistance programs, and local costs all affect your real closing number.
Tampa veterans and active-duty members, here's exactly what it takes to qualify for a VA loan in 2026 — from service requirements to the COE process.
Buying a home before selling in Tampa means carrying two mortgages temporarily. Here's how bridge loans, HELOCs, and other financing structures make it work.
Changing jobs doesn't disqualify you from a Tampa mortgage. Learn what lenders actually need to approve your loan after a job change.
A Tampa mortgage broker shops wholesale rates across multiple lenders to find the best fit for your loan file — here's how the process actually works.
Choosing between a HELOC and a home equity loan in Tampa? This guide breaks down how each works so you can match the right product to your financial situation.
Think a national bank is faster or cheaper for a Tampa HELOC? The reality of underwriting, rate-setting, and service tells a different story.
Refinancing a Tampa home loan saves money only when your closing costs — including Florida's unique mortgage taxes — are recovered before you sell or refinance again.
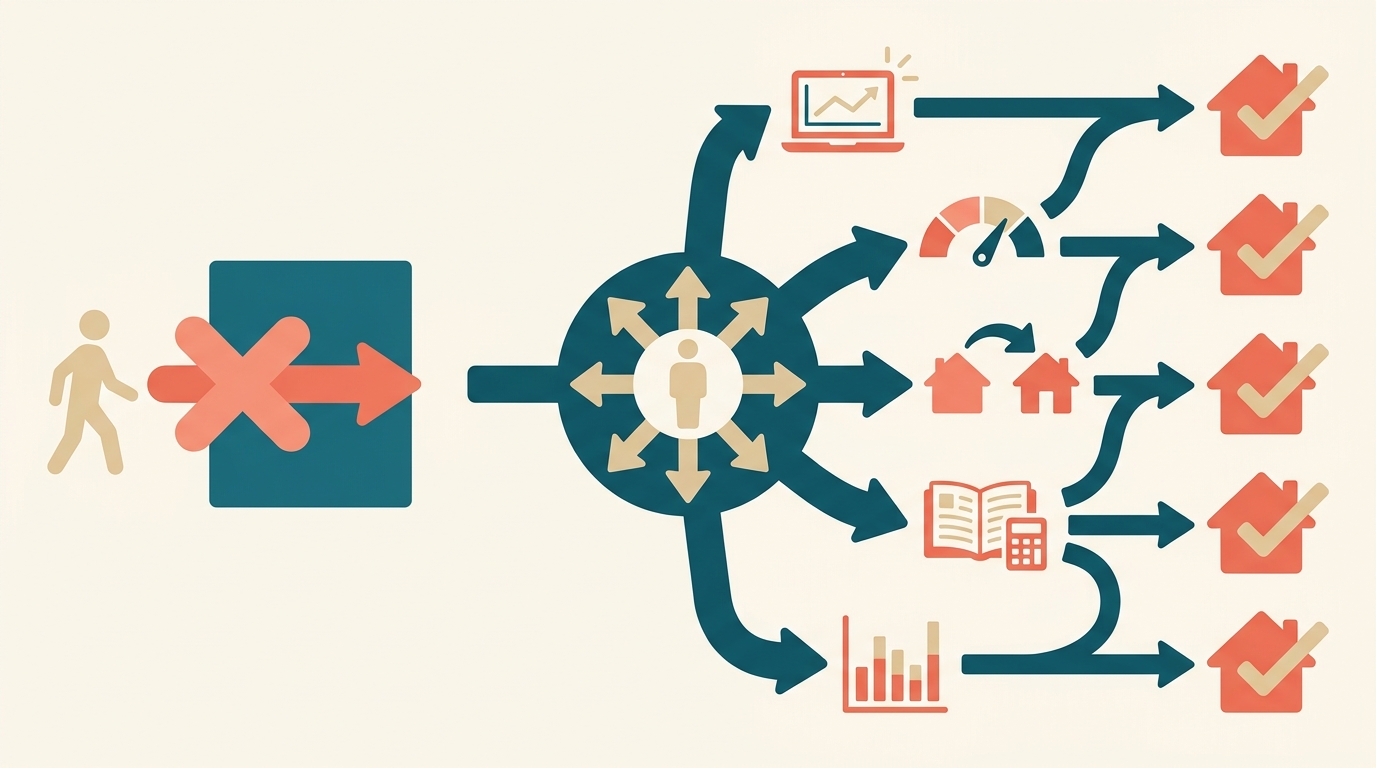
Complicated mortgage file? Tampa borrowers with self-employment, credit events, or non-standard situations can still get approved — here's how in 2026.
Locked in a low mortgage rate in Tampa? A HELOC or second mortgage lets you access your home equity without giving up your existing rate.
Financing a Tampa investment property means stricter equity, reserve, and income standards than a primary home. Here's what lenders actually require.
Tampa homeowners with equity and a high rate have real refinancing power — but only if the math works. Here's how to know when it pays.
Not sure whether a HELOC or cash-out refinance makes sense in Tampa? Compare 2026 rates, structures, and tradeoffs to find the right fit for your equity.
From buying discount points to refinancing, here are four practical ways to lower your mortgage rate in Tampa right now — with real numbers to guide your decision.
The 43% DTI limit on FHA loans is a myth. Tampa buyers may qualify with back-end ratios up to 56.99% — here's what the rules actually say.
In South Tampa's high-price market, an independent mortgage broker often beats a big bank on rate and flexibility — here's how the matchup plays out.
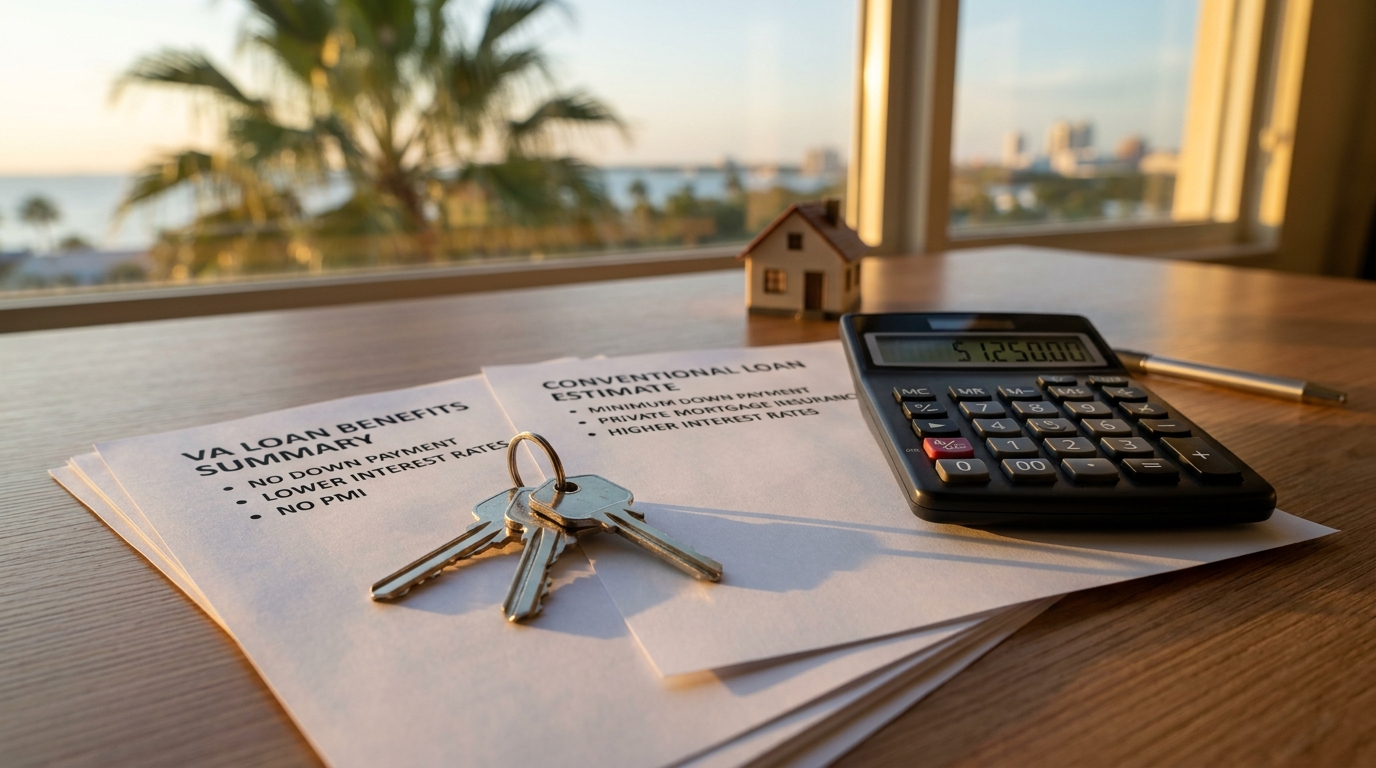
VA loans offer zero down and no mortgage insurance for eligible Tampa buyers, but conventional loans have advantages too. Here's how to choose in 2026.
From pre-approval to closing, here's exactly how the mortgage process works for first-time buyers in Tampa — including the local surprises that can derail your budget.
From conventional loans to DSCR financing, here's how Tampa rental property investors actually structure their purchases and scale their portfolios.
Tampa mortgage broker fees run 1–2% of your loan and appear differently depending on who pays. Here's how to read every line on your Loan Estimate.
Self-employed Tampa buyers qualify faster through a mortgage broker than a retail bank — brokers unlock bank-statement loans and non-QM programs most banks don't offer.
Wondering what credit score you need to buy a home in Tampa? From FHA minimums to conventional thresholds, here's what actually gets you approved in 2026.
Qualifying for a Tampa home loan in 2026 comes down to income, credit, DTI, and your loan program. Here's how each piece fits together in Tampa's market.
Buying a rental in Tampa means clearing three big hurdles: down payment, six-month reserves, and debt-to-income ratios. Here's what lenders actually require.
In Tampa, mortgage pre-approval typically takes 1–3 business days and moves through five key stages. Here's what to expect and how to fast-track your letter.
Tampa mortgage brokers charge 0.5%–2% borrower-paid or 1%–2.75% lender-paid — here's how to know which model actually costs you less.
A Florida HELOC lets you borrow against home equity as a revolving credit line, but homestead laws add unique signing rules and lender rights Tampa homeowners must know.
From W-2s to flood zone disclosures, here's the complete mortgage document checklist for Tampa buyers in 2026.
Refinancing in Tampa isn't one-size-fits-all. Learn the key differences between rate-and-term and cash-out refinances to find the right fit for your goals.
Not all first-time buyer loans work the same in Tampa. Compare FHA, USDA, and Florida Housing Bond programs to find your best fit.
Refinancing in Tampa follows a predictable path. Here's a clear, step-by-step walkthrough of what the process actually looks like for Florida homeowners in 2026.
Your bank can only offer its own rates — but a Florida mortgage broker shops dozens of lenders to find you a better deal.
Choosing between FHA and conventional loans in Tampa comes down to your credit score and savings. Here's an honest breakdown to help you decide.
Not all mortgage lenders work the same way. Here's how brokers and bankers differ in Tampa — and which one could save you thousands.
The right questions can save you thousands and prevent a deal from falling apart. Here's what to ask any Tampa mortgage broker before you commit.
Not all Tampa mortgage broker rankings are created equal. Here's what the criteria actually mean and how to compare brokers like a careful buyer.
With Tampa's median home price near $443K, choosing the wrong mortgage broker can cost you thousands. Here's how to vet one you can actually trust.
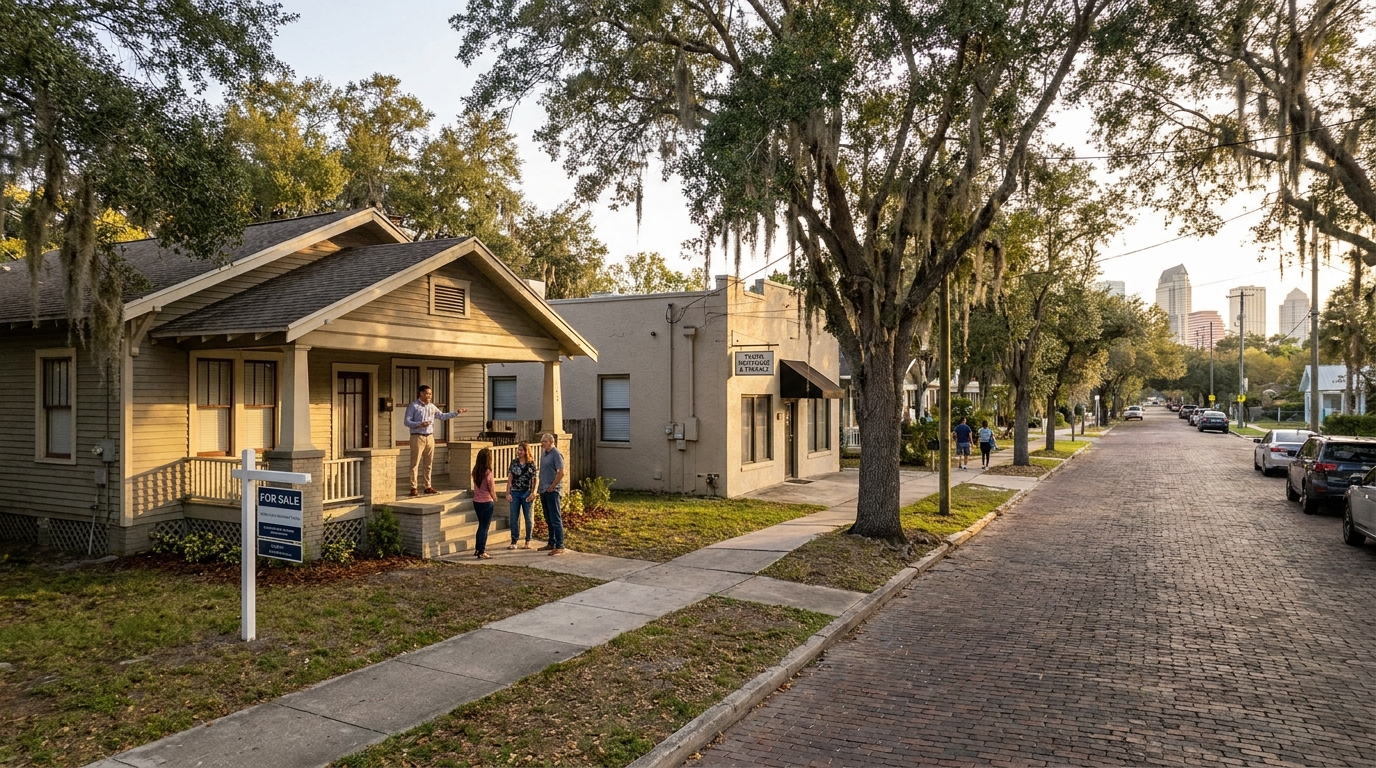
Financing a 1925 Seminole Heights bungalow isn't like buying a new build. Here's how to choose the right mortgage lender for Tampa's unique older neighborhoods.
Buying a home in Citrus Park? Here's how mortgage brokers and direct bank lenders actually compare — and how to choose the right path for your purchase.
Buying in Palma Ceia means finding a lender who understands South Tampa's competitive market. Here's how to compare your mortgage options effectively.
Not all refinance lenders are equal in Westchase. Learn which lender type — broker, bank, or credit union — gets Tampa homeowners the best rate for their situation.
Before you make an offer in Beach Park, you need a pre-approval letter. Here's exactly what Tampa lenders look for and how the process unfolds.
FHA or conventional? Ballast Point buyers face this fork every time. Here's how to choose based on your credit score, down payment, and long-term costs.
Learn FHA loan requirements for Tampa Bay homebuyers, including credit score minimums and down payment options for the local market.
Most mortgage delays are avoidable. Learn how to speed up your Tampa mortgage approval and close in 21 days instead of 45.
Current Tampa mortgage rates range from 5.75% on 15-year loans to 6.78% on cash-out refis, with 30-year fixed at 6.50%.
VA loans offer military families unbeatable advantages including zero down payment and no PMI. Learn how to maximize this lifetime benefit in Tampa's market.
FHA loans vs conventional loans for Tampa first-time buyers. Get the insider guide to loan options that actually work in today's market.
Get Tampa's best refinance rates. Compare 15+ lenders, FHA vs conventional terms, and avoid costly mistakes most borrowers make.
Get straight answers to your Tampa mortgage questions. VA loans, conventional options, and insider tips from a 15-year local broker.